
Key Takeaways
- Starting CPP at 60 permanently reduces the monthly pension by 36% compared with starting at 65.
- In the $1,000-at-65 example, waiting until 70 means giving up $60,000 over the preceding five years.
- A higher CPP payment at 70 may suit people who can fund the gap and want more guaranteed income later.
What if waiting five years for a bigger pension meant giving up $60,000 in payments along the way?
That's the dilemma facing Canadians deciding when to start collecting the Canada Pension Plan (CPP).
Start at 60, and you get money sooner. Wait until 70, and your monthly payment could be substantially bigger.
But here's the twist: the biggest monthly cheque doesn't always mean the most money over your lifetime.
How Much Does Your Starting Age Change CPP?
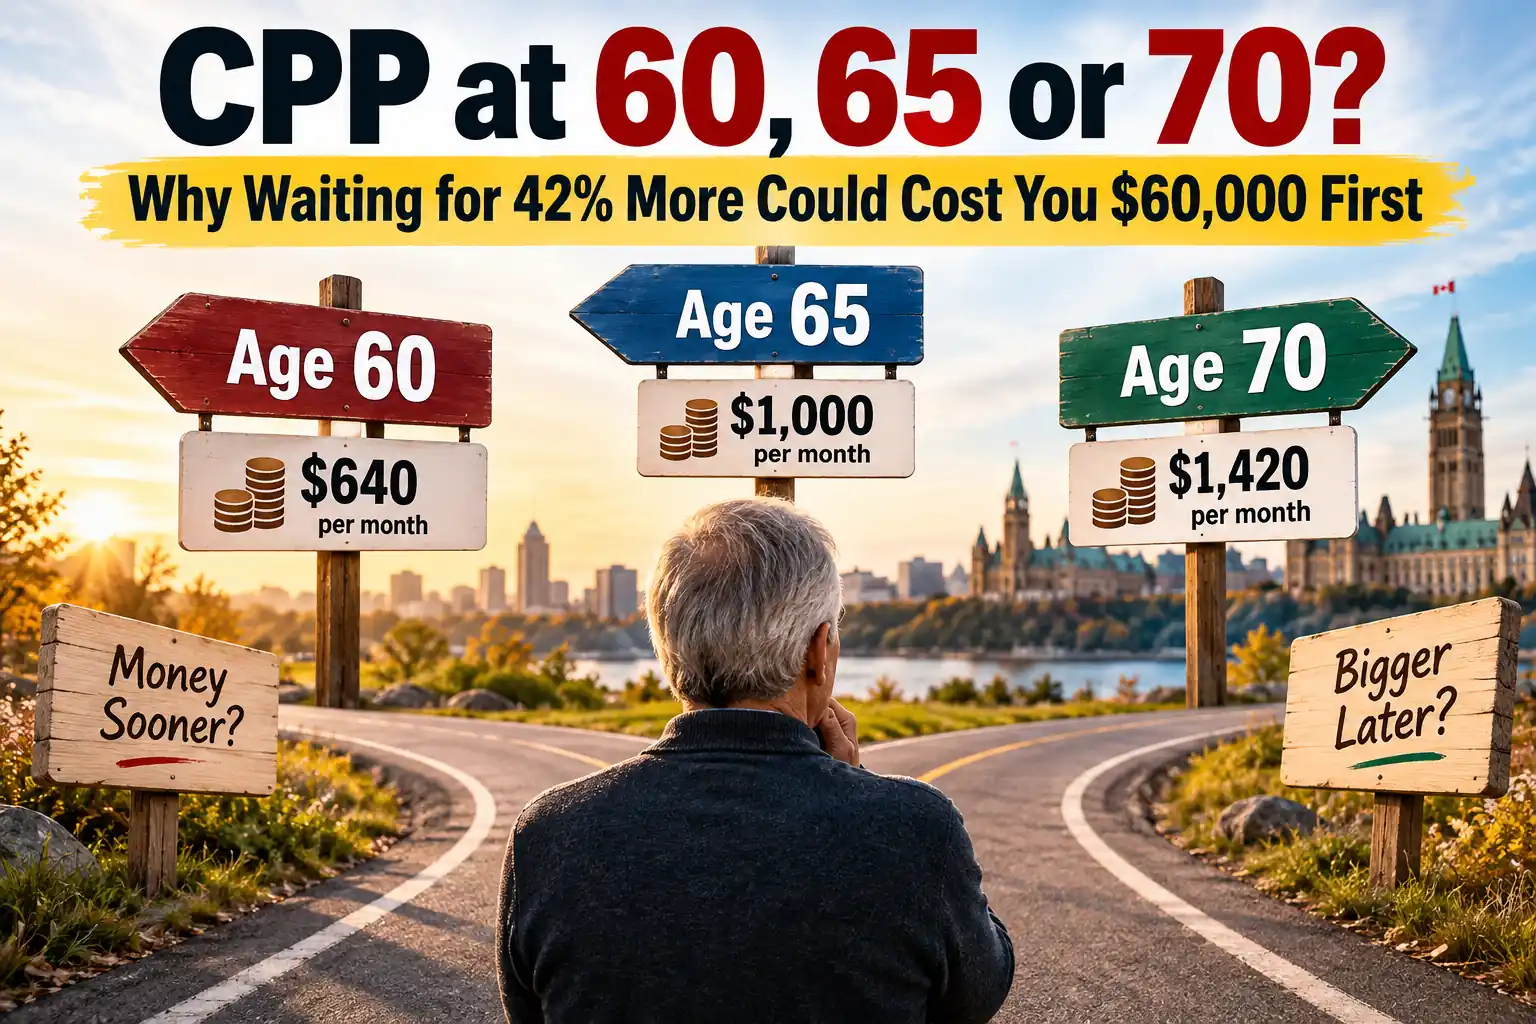
Under Canada's CPP rules, starting at 60 reduces your monthly pension by 36% compared with age 65. Waiting until 70 increases it by 42%.
Suppose your estimated pension at 65 is $1,000 a month.
| Start age | Monthly CPP |
|---|---|
| 60 | $640 |
| 65 | $1,000 |
| 70 | $1,420 |
These are hypothetical amounts illustrating the age adjustments, not personal benefit estimates.
Looking at those numbers, waiting until 70 seems like an easy decision.
Until you do the math.
The $60,000 Surprise
Someone starting CPP at 65 receives $1,000 monthly for five years.
That's $60,000 collected before age 70.
Someone waiting until 70 receives nothing during that period.
Once the later starter begins collecting $1,420 monthly, they're earning $420 more.
But catching up with that $60,000 head start takes approximately 12 years.
That means the person who waited until 70 doesn't catch up in cumulative payments until around age 82.
This is simplified arithmetic, excluding taxes, inflation adjustments, investment returns and differences in contributions. Your actual break-even age may differ.
And living longer changes the outcome.
Why Starting at 60 Could Be the Right Move
Imagine you're 60, exhausted from working and struggling with expenses.
Would you prefer a smaller pension today or a bigger one ten years from now?
Starting early could help cover bills, reduce debt or allow you to work fewer hours.
Health and life circumstances matter, too.
But there's a permanent trade-off: starting early means a smaller base pension for life, although payments receive inflation adjustments.
Why Waiting Until 70 Could Be Worth It
Now imagine you're healthy, financially secure and worried about running out of savings at 90.
Waiting until 70 provides a larger monthly CPP payment for life.
CPP also receives annual cost-of-living adjustments.
That bigger payment can become especially valuable during a long retirement.
The challenge? You must fund your living expenses while waiting.
One More Catch: Taxes and GIS
CPP is taxable income.
For some lower-income retirees, CPP payments can also affect the Guaranteed Income Supplement (GIS).
So an extra $420 in gross CPP doesn't necessarily translate into $420 more spending money.
And collecting CPP doesn't mean you must stop working. Eligible workers can continue contributing and earn additional post-retirement benefits.
So, Should You Start at 60, 65 or 70?
There isn't one perfect age.
Start earlier if you need income now and understand the lifelong reduction.
Consider waiting if you can afford the gap and want stronger guaranteed income later.
Choose 65 if it best fits your retirement and financial needs.
Before applying, check your personal estimates through My Service Canada Account.
Because retirement isn't about winning a spreadsheet competition.
It's about making sure your money lasts as long as you do.
This article provides general information, not personalized financial advice.