Twikup logo
Twikup

Topic

Retirement

In Money

Latest in Retirement

Newest first
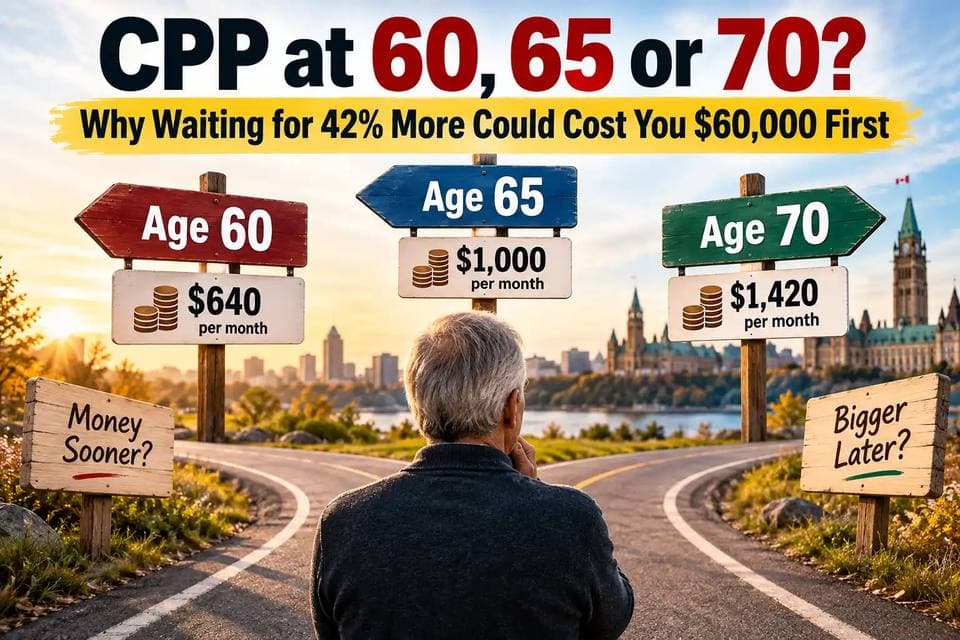
CPP at 60, 65 or 70? Why Waiting for 42% More Could Cost You $60,000 First

Money

CPP at 60, 65 or 70? Why Waiting for 42% More Could Cost You $60,000 First

Canadians can start CPP at 60, 65 or 70, with a permanent reduction for starting early and a larger monthly payment for delaying. Using a hypothetical $1,000 monthly pension at 65, this guide shows why waiting until 70 can mean forgoing $60,000 in earlier payments and explores break-even timing, taxes, GIS and personal retirement needs.

Oct 12, 2026•40 views today
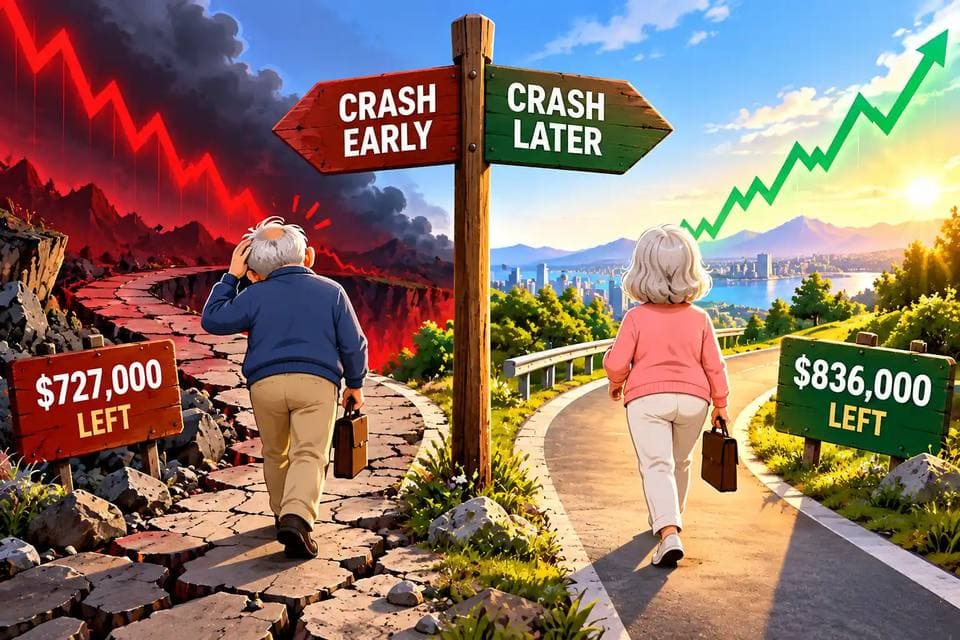
Why a Market Crash Early in Retirement Can Drain Your Savings Faster

Money

Why a Market Crash Early in Retirement Can Drain Your Savings Faster

Two retirees can start with the same $1 million, withdraw the same amount and earn the same average returns, yet end up with dramatically different balances. This article explains sequence-of-returns risk: why market losses early in retirement can be especially damaging, how withdrawals magnify the effect and why smooth average-return projections can miss a critical retirement-planning risk.

Sep 24, 2026•25 views today
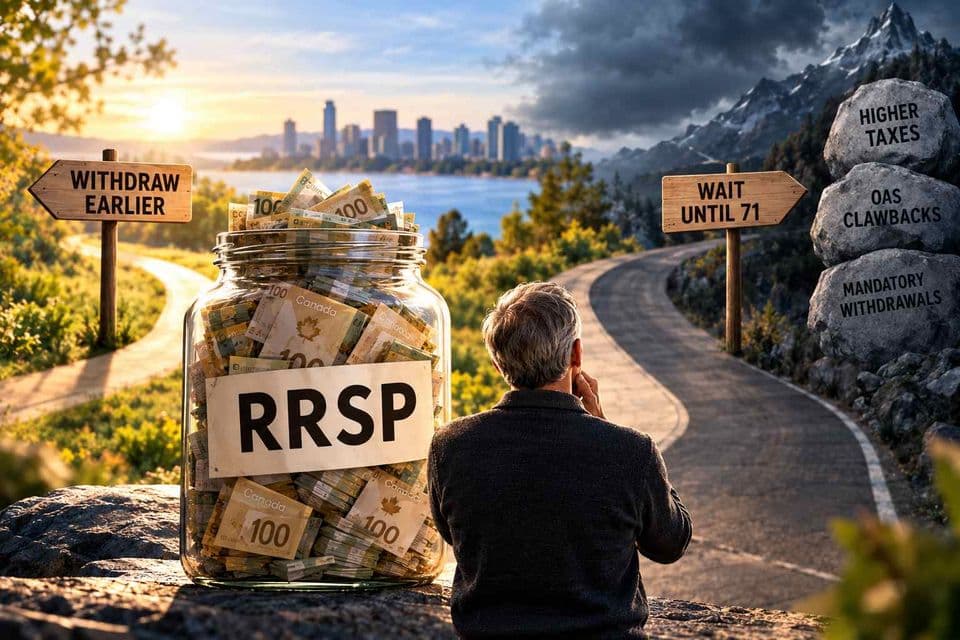
Your RRSP Can Become Too Big — Here’s Why Some Canadians Withdraw Before They Need the Money

Money

Your RRSP Can Become Too Big — Here’s Why Some Canadians Withdraw Before They Need the Money

An RRSP meltdown involves deliberately withdrawing registered savings during lower-income retirement years rather than leaving everything invested until mandatory RRIF withdrawals begin. Using David’s hypothetical $900,000 RRSP, this article explains how the approach may smooth taxable income, reduce future RRIF balances and potentially limit OAS recovery tax exposure—while outlining significant trade-offs and planning considerations.

Sep 22, 2026•33 views today
Most Canadians Are Saving for the Wrong Retirement Number

Money

Most Canadians Are Saving for the Wrong Retirement Number

Many Canadians believe retirement requires $1.7 million in savings, but financial planners say that figure can be misleading. Your actual target depends on lifestyle, location, pensions, and government benefits.

Jun 8, 2026•46 views today