
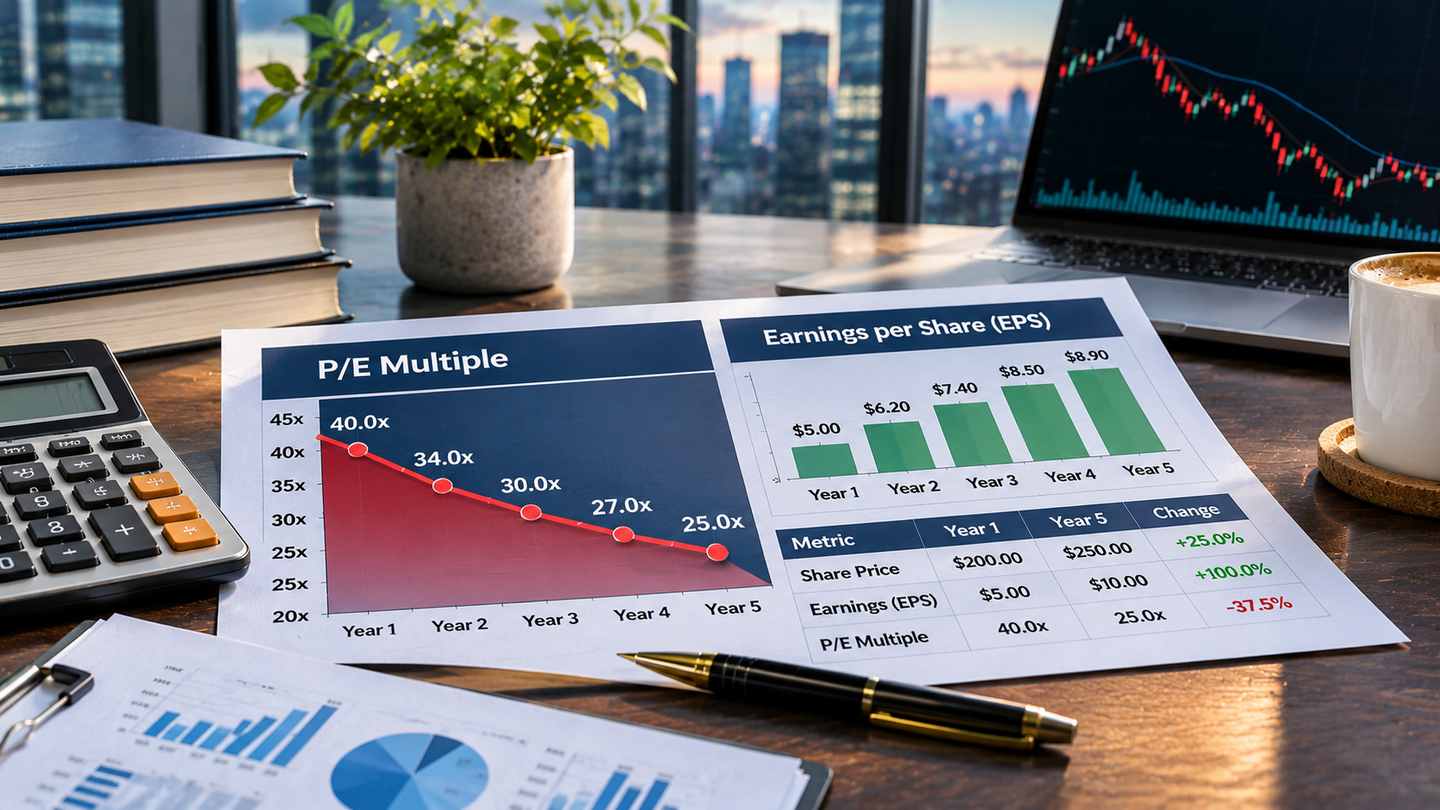
Key Takeaways
- A falling multiple can reflect improving valuation, but it can also signal that investors expect weaker future business performance.
- Temporary earnings increases can make a company appear cheaper even when its underlying profitability has not improved.
- Comparing valuation multiples without examining earnings quality, business risk and industry conditions can produce misleading investment conclusions.
The Stock Looks Cheaper. But Is It Really a Bargain?
A falling P/E ratio sounds like a sale. The stock costs less for every dollar of earnings, so surely it must be a better deal, right?
Not so fast.
A lower multiple can mean the market has handed you an opportunity. It can also mean earnings were flattered, expectations have fallen, or the business itself is getting weaker. The ratio alone doesn't tell you which story is true.
Think of it like a price tag with no context. You need to know whether the price fell, earnings jumped, or both moved at once — and why.
What a Falling P/E Ratio Actually Measures
A price-to-earnings (P/E) ratio divides a stock's price by its earnings per share. When the ratio falls, one of two things happened: the price declined, earnings rose, or both moved in a way that reduced the multiple.
Take a simple example:
- A stock trading at $50 with earnings of $5 per share has a P/E of 10.
- If the price falls to $40 while earnings stay at $5, the P/E falls to 8.
- If earnings instead rise to $6.25 while the price stays at $50, the P/E also falls to 8.
Same ratio. Very different stories.
In the first case, the market is marking the stock down. In the second, the business is earning more. That's why a falling P/E is a prompt to investigate, not a verdict.
Why the Ratio Can Fall Without a Bargain
A falling P/E can be misleading for several reasons:
- One-time earnings can make the multiple look lower than it really is. If profits were inflated by one-time gains or generated from an asset sale, and those earnings do not repeat, the stock may not be as inexpensive as the multiple suggests.
- Falling expectations can push the price down. The market may expect weaker future earnings, so the stock is not necessarily cheaper in a meaningful sense; it is adjusting to lower expectations.
- A shrinking denominator can distort the picture too. Earnings are falling, so the denominator gets smaller. That usually pushes the ratio higher, not lower. But it also shows why timing matters: a single snapshot may not reflect a stable earnings stream.
In each case, the ratio is a snapshot, not a verdict.
Why Earnings Quality Matters More Than the Headline Number
Earnings are not always straightforward. Companies can report profits that include one-time items, accounting adjustments or gains that do not reflect ongoing operations.
A P/E based on those earnings may look low even if the core business is weakening.
That's why investors often look beyond the headline figure to:
- adjusted earnings
- free cash flow
- revenue trends
Together, these help show whether reported profits are supported by the underlying business. If earnings quality is poor, a falling P/E may hide more risk than it reveals.
The Value Trap: When “Cheap” Keeps Getting Cheaper
A value trap occurs when a stock looks cheap on valuation measures but continues to decline because its business is deteriorating.
Falling prices can create the appearance of value while the company's prospects are getting worse.
This is why a lower P/E is not enough on its own. A stock can become cheaper and still be overvalued relative to its future earnings power.
The key question is not simply whether the multiple has declined. It's whether the business can sustain or grow its earnings.
What Should Investors Compare Instead?
A P/E ratio is more useful when placed in context. Investors may compare:
- Sector context: the sector's average P/E, because some industries normally trade at lower multiples.
- Historical range: the company's own historical range, since a “low” ratio may still be high for that business.
- Earnings direction: whether earnings are rising, stable or deteriorating.
- Financial strength: whether debt, cash flow and competitive position support the current price.
- Reason for the fall: whether the price decline reflects temporary market sentiment or a durable change in the business.
These comparisons separate a genuine opportunity from a warning sign.
The Twikup Take
A falling P/E is a clue, not a conclusion. Before you call a stock cheap, check why the ratio fell, whether earnings are real and repeatable, and whether the business can keep earning. That's how you tell a bargain from a trap.
This article is for educational and informational purposes only and should not be considered financial or investment advice. P/E ratios are valuation tools, not guarantees of future returns. Investors should conduct independent research and consult a qualified financial professional when necessary.
Image: AI-generated illustration.