
Key Takeaways
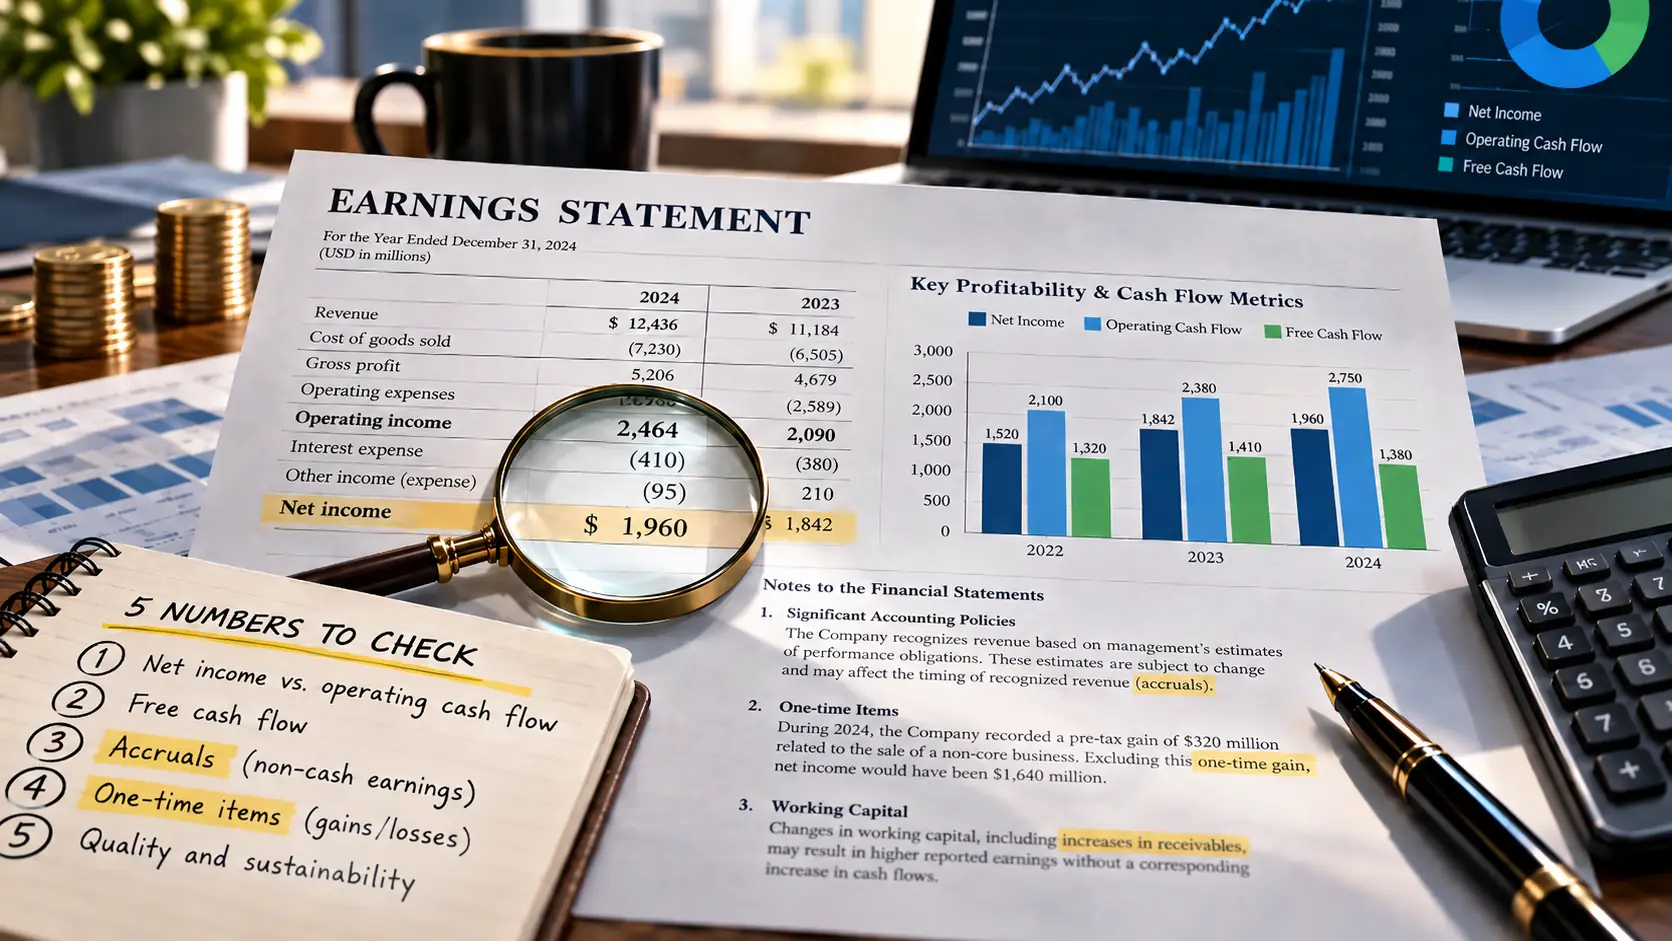
- Compare operating cash flow with net income over several years to see whether reported earnings are converting into cash.
- Free cash flow shows what remains after capital expenditures and can reveal a different picture than operating cash flow alone.
- Check receivables, inventory and one-time items to separate recurring business performance from temporary accounting gains.
A company announces record profits.Revenue is growing. Earnings per share beats expectations. Management sounds confident.
The stock jumps.
Everything looks great.
But there is one problem investors often miss:
Accounting profit and actual cash generation are not always the same thing.
A business can report rising net income while cash flow weakens. It can boost earnings through accounting estimates, asset sales or temporary tax benefits. It can even appear profitable while spending far more cash than it generates.
That does not automatically mean something is wrong.
But it does mean investors should look beyond the headline profit number.
Here are five numbers that can help you judge whether a company's profits are actually sustainable.
1. Net Income: Start Here, But Don't Stop Here
Net income is the familiar "bottom line."
It tells you how much profit remains after expenses, interest, taxes and other accounting adjustments.
Suppose a company reports:
Revenue: $1 billion
Net income: $120 million
That gives it a net profit margin of 12%.
At first glance, that sounds healthy.
The problem is that net income is based on accounting rules, and accounting profit can include revenue that has not yet been collected in cash, expenses spread across several years and one-time gains that may never happen again.
So net income is useful.
But by itself, it does not tell you how much cash the business actually produced.
That leads to the second number.
2. Operating Cash Flow: Is the Profit Turning Into Cash?
Operating cash flow measures the cash generated by a company's normal business activities.
For many investors, this is one of the most important numbers to compare with net income.
Imagine two companies each report $100 million in net income.
Company A generates $140 million in operating cash flow.
Company B generates only $40 million.
The accounting profits look identical.
The cash economics do not.
Company A may be collecting payments quickly and converting sales into real cash.
Company B may have large amounts tied up in unpaid customer bills, inventory or other working-capital items.
A simple comparison can be useful:
Operating cash flow ÷ net income
If operating cash flow repeatedly exceeds or roughly tracks net income, earnings may be supported by strong cash generation.
If net income keeps rising while operating cash flow consistently falls behind, that deserves investigation.
One weak quarter does not prove anything. Working capital can move significantly from quarter to quarter.
The trend over several years matters more.
3. Free Cash Flow: What's Left After Keeping the Business Running?
Operating cash flow still does not tell the entire story.
Companies often need to spend money on factories, equipment, data centres, stores, vehicles, servers or other long-term assets just to maintain and grow the business.
That is why investors frequently look at free cash flow.
A simple version is:
Free cash flow = operating cash flow − capital expenditures
Suppose a company generates $200 million in operating cash flow but spends $170 million on capital expenditures.
Its free cash flow is only about $30 million.
Another company generates $170 million in operating cash flow but needs only $40 million in capital expenditures.
Its free cash flow is approximately $130 million.
The second company produces less operating cash flow but has far more cash left after investment.
That cash can potentially be used to reduce debt, repurchase shares, pay dividends, make acquisitions or reinvest in growth.
However, capital spending is not automatically bad.
A rapidly expanding company may intentionally spend heavily today to build assets that generate much larger profits later.
The key question is whether that spending produces attractive future returns.
4. Accruals: How Much Profit Hasn't Become Cash Yet?
This is where earnings analysis becomes especially interesting.
Accounting uses accruals because businesses often earn revenue and incur expenses at different times from when cash actually changes hands.
That is normal.
But unusually large accruals can sometimes make reported earnings look stronger than cash generation.
Consider a company that sells $100 million worth of products in December.
Customers do not have to pay until several months later.
The company may record much of that revenue immediately even though the cash has not yet arrived.
If accounts receivable starts rising much faster than revenue, investors should ask why.
Perhaps customers are simply receiving longer payment terms.
Or perhaps the company is struggling to collect money.
Inventory can tell a similar story.
If revenue grows 10% while inventory rises 40%, it may indicate the company is preparing for strong future demand.
But it could also mean products are not selling as quickly as expected.
There is rarely one magic accrual number that proves earnings are weak.
Instead, compare trends in:
- accounts receivable
- inventory
- accounts payable
- net income
- operating cash flow
The bigger the disconnect between accounting profit and cash generation, the more questions investors should ask.
5. One-Time Items: Did the Company Make Money From Its Business?
Now imagine a company normally earns around $80 million per year.
This year, net income suddenly jumps to $200 million.
Fantastic result?
Maybe.
But then you discover that the company sold a building and recorded a $130 million gain.
The core business may actually have earned less than the previous year.
One-time items can include things such as asset sales, restructuring charges, lawsuit settlements, insurance recoveries, acquisition-related costs, impairment charges and unusual tax benefits.
Not all of them are suspicious.
Real companies regularly experience unusual events.
The important question is:
Would this profit probably happen again next year?
If the answer is no, investors should separate it from the recurring economics of the business.
A Simple Earnings Quality Test
Imagine a company reports:
Net income: $500 million
Operating cash flow: $620 million
Capital expenditures: $170 million
Free cash flow: $450 million
One-time gains: $20 million
That picture looks relatively straightforward.
Most reported profit is supported by cash generation, and free cash flow remains strong after capital spending.
Now compare another company:
Net income: $500 million
Operating cash flow: $210 million
Capital expenditures: $180 million
Free cash flow: $30 million
One-time gains: $160 million
Both companies technically reported $500 million in net income.
But economically, they look very different.
The second company's headline profit is supported by much less cash and includes a much larger one-time contribution.
That does not automatically make it a bad investment.
It simply tells you that the $500 million headline deserves much closer examination.
The TwikUp Perspective
One of the easiest mistakes in stock investing is treating reported profit as if it were cash sitting in a bank account.
It isn't.
Net income is an accounting measurement. Operating cash flow tells you how much cash the business is generating from operations. Free cash flow shows what remains after major capital spending. Accruals reveal where accounting earnings and cash timing may be diverging. One-time items help determine how much of today's profit might actually be repeatable.
The strongest businesses often show a recognizable pattern over time:
profits grow, operating cash flow follows, and free cash flow eventually follows as well.
When those three numbers move together for years, the financial story becomes easier to trust.
When reported profit races higher while cash generation repeatedly moves in the opposite direction, the story deserves more investigation.
The goal is not to find a perfectly clean income statement.
Almost no company has one.
The goal is to understand where the profit is coming from — and whether the business can reasonably keep producing it.