
Key Takeaways
- Different fund names can still produce overlapping exposure to the same companies and sectors.
- Calculate combined dollar exposure across funds to understand how much you own of a single company.
- Diversification can reduce certain risks, but it cannot eliminate losses in a broad market crash.
John Invested $25,000 in Five Different Places. Then He Discovered a Hidden Risk.
John thought he was being smart with his money.
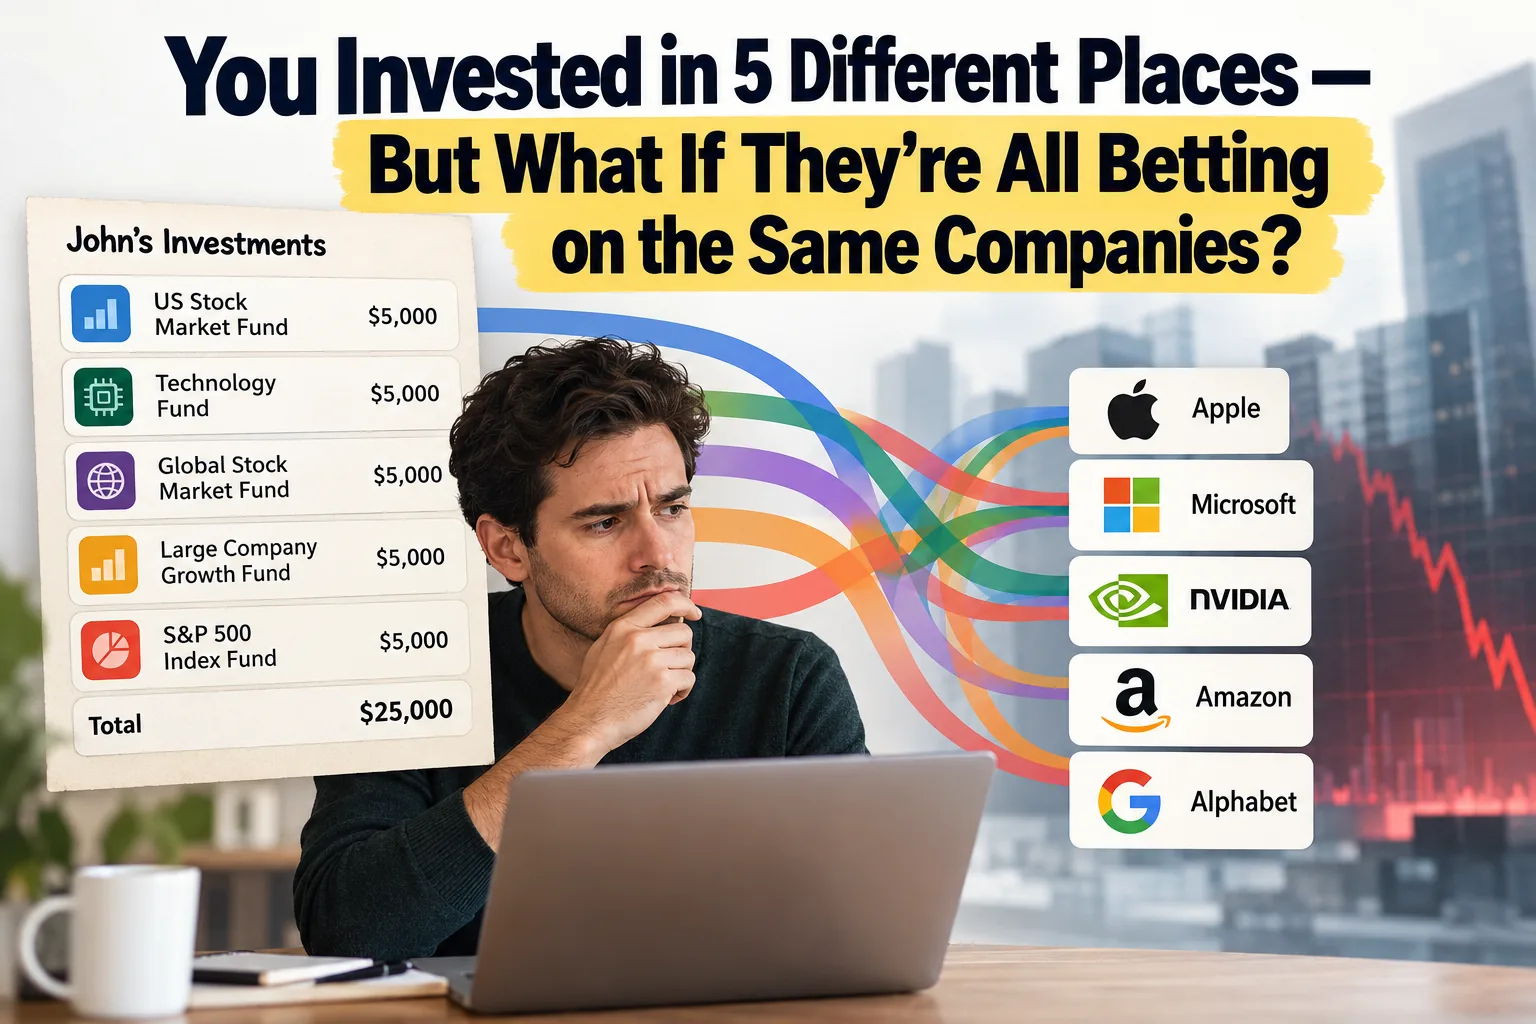
He had saved $25,000 and decided not to put everything into one investment. Instead, he divided his savings equally among five funds.
His investment account looked like this:
| Investment | Amount |
|---|---|
| US Stock Market Fund | $5,000 |
| Technology Fund | $5,000 |
| Global Stock Market Fund | $5,000 |
| Large Company Growth Fund | $5,000 |
| S&P 500 Index Fund | $5,000 |
| Total | $25,000 |
Five different funds. Five different names.
John felt pretty good about himself.
He had followed one of the oldest rules of investing: never put all your eggs in one basket.
There was just one problem.
What if all five baskets contained many of the same eggs?
John was about to discover something that millions of investors could easily overlook.
John is a fictional investor. All portfolio examples and calculations are hypothetical.
The $25,000 Surprise John Never Expected
One evening, John decided to see which companies his funds actually owned.
He opened the first fund.
Apple. Microsoft. Nvidia. Amazon.
Nothing unusual.
Then he checked the second fund.
Microsoft. Nvidia. Apple.
Interesting.
He opened the third.
There they were again.
By the time John finished reviewing his investments, he noticed that several familiar companies appeared across multiple funds.
It was like ordering five different meals at a restaurant and discovering that every dish contained the same main ingredient.
The names on the menu were different. The ingredients weren't.
Here's why this happens.
An S&P 500 fund may own Microsoft because it belongs to the index. A technology fund may hold Microsoft because it's a major technology business. A global fund might include it because American companies are part of the global market.
None of these funds is doing anything wrong.
But John had never considered how much of his money might be connected to the same businesses.
And that could become expensive.
How One Company Could Wipe Out $2,500 of John's Savings
Imagine John discovers something alarming.
After combining the holdings of his five funds, he calculates that $6,250 of his $25,000 portfolio is exposed to one company.
That's one-quarter of everything he invested.
Now suppose that company has a terrible year.
Its stock price drops 40%.
What happens to John's money?
| What happens | Amount |
|---|---|
| Original portfolio | $25,000 |
| Exposure to one company | $6,250 |
| Company's stock decline | 40% |
| Loss from that company | -$2,500 |
| Portfolio after this loss | $22,500 |
Just like that, John has lost 10% of his entire portfolio because of one company's decline, assuming every other holding stays unchanged.
Here's the surprising part.
John never bought that company's stock directly.
He purchased funds, and those funds bought shares on his behalf.
To be clear, this is an intentionally extreme illustration. A 25% position in one company would be unusually high for many broad-market fund portfolios.
But it demonstrates something important.
You can have five investments on your screen and still have a surprisingly large amount of money riding on one business.
Your Fund Owns 500 Companies. So Why Do Just a Few Matter So Much?
Suppose someone tells you their investment fund owns 500 different companies.
Sounds safe, right?
Surely, if one company struggles, the other 499 can help balance things out.
But there's a catch.
Many popular stock market funds don't divide money equally among every business.
Instead, larger companies receive a bigger allocation.
Imagine a classroom with 500 students taking a group exam.
Everyone contributes to the final grade, but the teacher gives the biggest 10 students far more influence over the result.
Even if hundreds of other students perform well, a terrible performance from those heavily weighted students could drag down the overall score.
Some stock funds work in a similar way.
A relatively small number of giant businesses can have a much greater influence on performance than hundreds of smaller holdings.
This doesn't automatically make those funds bad investments.
It simply means that owning hundreds of stocks isn't the same as spreading your money equally across hundreds of companies.
And when you purchase additional funds containing those same giants, you may be adding more exposure than you realize.
Three Friends, Three Portfolios. Who Actually Has Less Risk?
Let's make things interesting.
John meets two friends for coffee.
Naturally, the conversation turns to investing.
Sarah says she owns one broad US stock market fund.
David proudly announces that he owns three: an S&P 500 fund, a Nasdaq-100 fund and a technology fund.
John smiles.
He owns five.
"So I'm the most diversified here," he thinks.
Not necessarily.
Sarah's single fund could provide exposure to companies across numerous industries, including healthcare, banking, manufacturing and technology.
David's three funds could have substantial overlap in large technology businesses.
And John's five funds? Their diversification depends on how much each one invests in different companies and sectors.
The person with the most funds isn't automatically the person with the best-diversified portfolio.
There's another twist.
Even Sarah's broad-market investment can lose value during a market crash.
Diversification helps manage certain risks. It doesn't create an invisible shield around your savings.
And when markets panic, investments that normally behave differently can sometimes fall together.
The Five-Minute Investment Check Most People Skip
John didn't need an expensive financial adviser or complicated trading software to begin investigating his investments.
He needed something much simpler.
The holdings section of his investment account.
Most fund providers publish information about the companies their funds own.
Here's how you can investigate your own portfolio.
Step 1: Find out what's inside.
Open your investment app or fund provider's website. Look for "Holdings," "Portfolio Composition" or "Top 10 Holdings."
Step 2: Look for familiar names.
If Apple, Microsoft, Nvidia or another company appears repeatedly, make a note of it.
Step 3: Check the percentages.
This is where things get interesting.
A company representing 2% of one fund is very different from a company representing 15% of another.
Simply appearing twice doesn't tell you how much money is involved.
Step 4: Do the math.
Suppose you own two funds.
| Fund A | Fund B | |
|---|---|---|
| Your investment | $10,000 | $15,000 |
| Allocation to Company X | 8% | 6% |
| Your exposure | $800 | $900 |
Together, you've invested $25,000.
But $1,700 of that money is connected to Company X.
That's 6.8% of your total investment.
Now you have a clearer picture of what you actually own.
Remember, the top 10 holdings are only a starting point. For a complete overlap analysis, you may need each fund's full holdings list.
And because fund allocations change over time, this isn't necessarily a one-time exercise.
Should You Stop Buying Multiple Funds?
Absolutely not.
Imagine John discovers that his portfolio contains overlapping investments.
Should he immediately sell four funds and keep just one?
Not necessarily.
Multiple funds can provide valuable diversification when they invest in genuinely different markets, industries, company sizes or asset classes.
For example, an investor might combine domestic and international stocks with bonds, depending on their goals and risk tolerance.
The important distinction is whether each investment adds something useful.
Think about building a football team.
Having five excellent strikers doesn't necessarily make your team stronger if you have no defenders or goalkeeper.
You need players performing different roles.
Investing can work the same way.
A portfolio needs a mix that suits its purpose, not simply a long list of impressive names.
Some overlap is also completely normal. Large successful companies naturally appear in many major indexes.
Before making changes, consider your investment timeline, fees, taxes, financial objectives and how much risk you're comfortable taking.
TwikUp's Perspective: Five Restaurants, One Supplier, and a Very Expensive Lesson
Imagine you own five restaurants.
One serves pizza.
Another sells burgers.
The third specializes in Indian food.
The fourth serves sushi.
The fifth is a fancy steakhouse.
You're feeling confident because your income comes from five completely different businesses.
Then one morning, your main food supplier shuts down.
Suddenly, all five restaurants have a problem.
Different menus. Different customers. Different signs outside.
But behind the scenes, they depended on the same supplier.
That's the kind of hidden connection investors should look for.
John's mistake wasn't choosing five funds.
It was assuming that different investment names automatically meant different sources of risk.
And that's an easy assumption to make when an investing app displays five separate investments, each with its own performance chart.
The solution isn't to panic, abandon index funds or chase investments that never overlap.
It's to understand where your money actually goes.
Because having more investments doesn't always mean having more diversification.
The next time you open your portfolio and see five different funds, ask yourself one simple question:
"Have I spread my money across different opportunities, or have I accidentally bought the same companies five different ways?"
The answer might surprise you.