
Key Takeaways
- Market capitalization measures a company's equity value, while enterprise value accounts for debt, cash and other relevant financial claims.
- Two businesses with identical market caps can have dramatically different enterprise values because of their balance sheets.
- Investors should use market cap and enterprise value together when evaluating acquisitions, comparing businesses and examining stock valuations.
Why Can Two Companies With the Same Market Cap Have Different Values?
Imagine two companies, each valued at $50 billion in the stock market. At first glance, they appear equally valuable. However, one company has $15 billion in debt and only $2 billion in cash, while the other holds $10 billion in cash and carries almost no debt.
Would an investor evaluating the entire business consider them equally valuable?
Not necessarily.
The difference comes down to enterprise value and market capitalization. Market cap measures the market value of a company's equity, while enterprise value provides a broader picture by accounting for debt, cash and certain other financial claims.
This distinction matters because buying shares and acquiring an entire business are not the same financial decision. Investors who focus only on market capitalization may overlook significant obligations or valuable cash reserves.
What Is Market Capitalization and How Is It Calculated?
Market capitalization, commonly called market cap, represents the total market value of a company's outstanding shares.
The formula is:
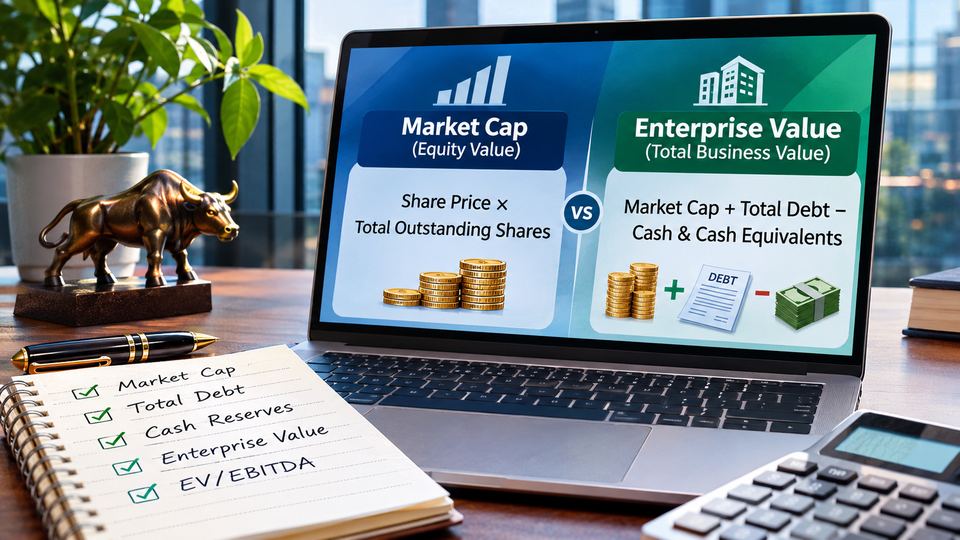
Market Capitalization = Current Share Price × Total Outstanding Shares
Consider a hypothetical company with 100 million outstanding shares trading at $50 each.
Its market capitalization would be:
$50 × 100 million = $5 billion.
This means investors currently value the company's equity at approximately $5 billion.
Market cap is useful for understanding company size and comparing businesses within an industry. Investors also use it to classify stocks into large-cap, mid-cap and small-cap categories.
However, market capitalization does not directly account for outstanding debt, available cash or other claims on the business.
That limitation becomes important when comparing companies with different financing structures.
What Is Enterprise Value and How Does It Work?
Enterprise value (EV) measures the broader value of a company's operating business by considering equity value, debt and cash.
A simplified formula is:
Enterprise Value = Market Capitalization + Total Debt − Cash and Cash Equivalents
A more comprehensive calculation may also include preferred stock, non-controlling interests and other relevant claims, depending on the company's financial structure.
Debt is added because an acquirer must account for outstanding borrowing obligations. Cash is subtracted because available cash can reduce the net financial cost of acquiring the business.
Enterprise value therefore helps investors compare companies without looking exclusively at how their operations are financed.
It is particularly useful when examining businesses with significantly different debt levels or cash reserves.
Enterprise Value vs Market Cap: A Practical Example
Consider two hypothetical companies with identical market capitalizations.
| Financial Measure | Company A | Company B |
|---|---|---|
| Market capitalization | $50 billion | $50 billion |
| Total debt | $15 billion | $2 billion |
| Cash reserves | $2 billion | $10 billion |
| Enterprise value | $63 billion | $42 billion |
Company A:
$50B + $15B − $2B = $63B
Company B:
$50B + $2B − $10B = $42B
Both businesses have the same market capitalization, but their enterprise values differ by $21 billion.
Company A carries considerably more debt and has fewer cash reserves. Company B has a stronger net cash position.
This example demonstrates why market capitalization alone cannot provide a complete picture of a company's financial obligations.
All figures are hypothetical and are used only to explain the valuation concept.
Why Does Debt Change a Company's Enterprise Value?
Debt can significantly influence how investors evaluate a business.
When a company borrows money to expand operations, purchase equipment or acquire another business, its market capitalization does not automatically increase by the amount borrowed.
However, its financial obligations increase.
Consider a business with a $20 billion market capitalization and $8 billion in debt. If it holds $3 billion in cash, its simplified enterprise value becomes $25 billion.
The additional debt increases enterprise value because an investor evaluating the entire business must account for those obligations.
Investors should also distinguish between short-term borrowings, long-term debt and lease-related liabilities. The treatment of leases and other obligations depends on the valuation methodology being used.
A company with substantial borrowing is not automatically a poor investment. Debt may support productive expansion. The important question is whether the business generates enough cash flow to manage its financial commitments.
Why Can Cash Reserves Reduce Enterprise Value?
Cash and cash equivalents can reduce enterprise value because they represent financial resources available to the company.
Imagine a business with a market capitalization of $30 billion, total debt of $4 billion and cash reserves of $9 billion.
Its simplified enterprise value is:
$30B + $4B − $9B = $25B.
Its enterprise value is lower than its market capitalization because its cash holdings exceed its debt.
However, investors should not automatically subtract every dollar reported as cash without examining its availability. Restricted cash, operational cash requirements and other financial commitments can affect how much cash is genuinely available for valuation purposes.
The quality and accessibility of a company's cash reserves matter just as much as the headline balance.
When Should Investors Use Enterprise Value Instead of Market Cap?
Both measurements serve different purposes.
Market capitalization is useful when comparing equity values, evaluating company size and examining shareholder-focused valuation measures such as the price-to-earnings ratio.
Enterprise value becomes particularly useful when comparing businesses with different capital structures.
For example, EV/EBITDA compares enterprise value with earnings before interest, taxes, depreciation and amortization. It helps investors examine business valuations while accounting for differences in debt and cash.
However, EV/EBITDA is not a complete measure of investment attractiveness. It does not directly account for capital expenditure, working capital requirements or the cost of debt.
Investors should combine valuation multiples with profitability, cash flow and financial risk.
For another perspective on stock valuation, read Is a Low P/E Stock Really Cheap? 7 Things Investors Must Check Before Buying. It explains why earnings quality, debt and business fundamentals matter when evaluating apparently inexpensive shares.
What Should Investors Check Before Comparing Enterprise Values?
Before comparing two companies, investors should examine several financial factors:
- Total debt: Review short-term and long-term borrowing obligations.
- Cash reserves: Determine how much cash is available after considering restrictions and operating requirements.
- Outstanding shares: Use an appropriate share count and consider dilution when calculating equity value.
- Other financial claims: Examine preferred stock, minority interests and relevant additional obligations.
- Cash flow generation: Assess whether the company can maintain operations and meet its financial commitments.
Investors should also examine how effectively management uses capital. Our guide, ROIC vs ROE: The Metric That Can Reveal a Better Business Before the Stock Price Does, explains why returns on capital and equity can reveal important differences in business quality.
TwikUp's Perspective
Market capitalization is often the first number investors notice when evaluating a publicly traded company. It is simple, widely available and useful for understanding how the market values a company's equity.
But the equity value is only one part of the financial picture.
A business carrying substantial debt may have a much higher enterprise value than its market capitalization suggests. Meanwhile, a cash-rich company may have a lower enterprise value despite having the same market cap as a competitor.
The real advantage comes from understanding both measurements rather than treating either as a complete valuation answer.
Investors who examine enterprise value alongside debt, cash flow, profitability and capital efficiency can develop a more balanced understanding of what a business is actually worth.
A company's stock market value may tell you what investors are paying for its shares. Its enterprise value helps reveal what stands behind that price.
Frequently Asked Questions
1. What is the difference between enterprise value and market capitalization?
Market capitalization measures the total market value of a company's outstanding shares. Enterprise value includes market capitalization, debt and certain other financial claims, while subtracting available cash. It therefore provides a broader view of business value.
2. Can enterprise value be lower than market capitalization?
Yes. Enterprise value can be lower than market capitalization when a company holds more cash than debt, assuming other financial adjustments do not change the calculation.
3. How do you calculate enterprise value?
A simplified formula is Enterprise Value = Market Capitalization + Total Debt − Cash and Cash Equivalents. More comprehensive calculations may include preferred stock and minority interests.
4. Why do investors use enterprise value instead of market cap?
Investors use enterprise value to compare businesses with different debt and cash positions. It is particularly useful for valuation measures such as EV/EBITDA.
5. Is a lower enterprise value always better for investors?
No. A lower enterprise value does not automatically mean a stock is undervalued. Investors should also examine profitability, cash flow, debt obligations, growth prospects and the company's ability to generate sustainable returns.
Disclaimer
This article is intended for educational and informational purposes only and does not constitute financial, investment or personalised investment advice. All company figures and comparisons are hypothetical. Actual enterprise value calculations depend on debt, cash availability, preferred stock, minority interests and other relevant financial claims. Investors should review official company filings and conduct independent research before making investment decisions. TwikUp does not guarantee investment returns or recommend buying or selling any particular security.